3 W. Main St, Suite 103
Irvington, NY 10533
Contact info
844.X-Caliber
(212.220.7040)
Newsletter Signup
Join Thousands of Readers Who Subscribe to Our Content.
HUD has opened up new FHA financing opportunities for multifamily sponsors considering build-to-rent communities, expanding the types of rental housing developments that can qualify for FHA-insured financing.
With the release of Mortgagee Letter 2026-12, HUD has established clearer eligibility and underwriting requirements for qualifying communities of detached single-family rental homes, duplexes, and triplexes. The guidance provides a more defined financing pathway for new construction under FHA 221(d)(4), as well as acquisition and refinancing of recently developed properties under FHA 223(f), giving sponsors another option to evaluate when structuring eligible transactions.
Also in October, HUD has released updated affordable housing tax credit designations, implemented additional property inspection scoring requirements, and announced an initiative to coordinate federal housing reviews.
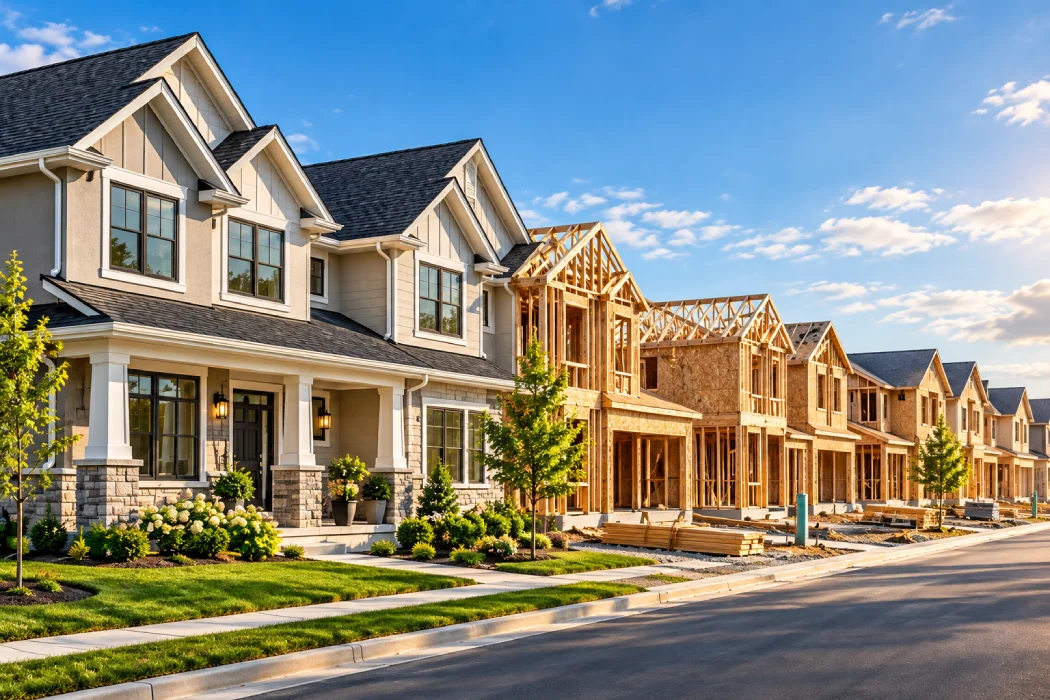
Effective immediately, qualifying build-to-rent developments can access FHA 221(d)(4) and 223(f) financing under newly established eligibility and underwriting requirements.
HUD has issued Mortgagee Letter 2026-12, formally expanding access to FHA multifamily mortgage insurance for qualifying build-to-rent (BTR) communities consisting of detached single-family rental homes, duplexes, or triplexes.
Historically, FHA multifamily financing has focused on developments with buildings containing four or more units. While some BTR properties have received FHA financing, eligibility has been limited and the requirements less clearly defined. The new guidance establishes a more consistent framework for evaluating these communities as multifamily rental properties.
Under the policy, qualifying BTR developments are eligible for two FHA financing programs:
To qualify, a development must contain at least five rental units on a cohesive, contiguous site and operate as a single, professionally managed multifamily property. Multiple contiguous tax parcels are permitted, but scattered-site properties are not. HUD also prohibits sales of individual parcels or buildings and partial collateral releases during the insured loan term.
The guidance also clarifies an important distinction for project design: detached single-family homes, duplexes, and triplexes are not considered “covered multifamily dwellings” under the Fair Housing Act’s accessibility design and construction requirements. As a result, certain accessibility standards that apply to traditional multifamily buildings do not apply to these individual dwelling types. However, applicable accessibility requirements remain in place for common areas and amenities, and other federal, state, or local accessibility laws may apply.
The Mortgagee Letter establishes specific underwriting considerations reflecting the characteristics of BTR developments. For new construction, HUD will consider an absorption period of up to 24 months, supported by detailed lease-up projections. The initial operating deficit escrow must be at least the greater of 3% of the loan amount or four months of debt service.
Vacancy assumptions must be at least 7% for market-rate properties, or the comparable market vacancy rate if higher, and at least 5% for affordable properties. HUD also calls for careful evaluation of operating expenses, replacement reserves, development and management experience, and applicable accessibility requirements.
For developers planning BTR communities and owners considering acquisition or refinancing, the new policy creates an opportunity to evaluate FHA financing for projects that may not previously have been considered conventional FHA multifamily candidates.
Project design, ownership structure, and applicable accessibility requirements will be important early considerations. Sponsors should also account for BTR-specific lease-up assumptions, operating costs, and reserve requirements when assessing financing feasibility.
The guidance is effective immediately, and HUD plans to incorporate its provisions into the Multifamily Accelerated Processing (MAP) Guide.
Read HUD Mortgagee Letter 2026-12
Updated geographic designations could influence tax credit equity and financing structures for affordable multifamily projects.
HUD has published its 2027 designations of Difficult Development Areas (DDAs) and Qualified Census Tracts (QCTs), two geographic classifications used to determine eligibility for certain benefits under the Low-Income Housing Tax Credit (LIHTC) program.
Projects located in qualifying DDAs or QCTs may be eligible for an increase of up to 30% in eligible basis, potentially increasing the amount of tax credits available to support development or rehabilitation. The benefit is subject to applicable LIHTC requirements and is not automatic for every project.
For affordable housing sponsors, the updated designations could affect project economics and financing structures. Additional tax credit equity may help close financing gaps, particularly for developments facing elevated construction costs or complex capital requirements.
The implications extend to projects combining FHA multifamily financing with LIHTC, including those using FHA 221(d)(4) for new construction or substantial rehabilitation.
The 2027 designations generally apply to tax credit allocations made after Dec. 31, 2026, with separate timing provisions for certain tax-exempt bond-financed projects. Sponsors with transactions planned for 2027 should review the updated designations and applicable timing rules to determine whether their projects qualify for additional tax credit equity.
Review HUD’s 2027 DDA and QCT designations
Previously deferred safety requirements are now included in HUD’s inspection scoring for applicable properties.
Beginning October 1, 2026, deficiencies associated with previously phased-in affirmative requirements under HUD’s National Standards for the Physical Inspection of Real Estate (NSPIRE) began counting toward inspection scores for applicable properties.
The requirements address building and resident safety conditions, including fire-labeled doors, electrical protection, guardrails, heating and cooling, and interior lighting.
HUD previously delayed scoring these requirements to give property owners additional time to prepare. With that transition period complete, identified deficiencies can now result in deductions from inspection scores.
The change applies to inspections conducted within HUD’s Public Housing and Multifamily Housing portfolios, including applicable HUD-assisted and insured properties.
HUD has also published proposed revisions to the NSPIRE scoring notice, with public comments due November 30, 2026.
Owners of properties subject to NSPIRE should review the newly scored requirements against existing property conditions and maintenance plans, particularly where deficiencies could require repairs or capital expenditures.
Inspection obligations vary by HUD program and property type, so owners should confirm which requirements apply to their properties.
Review HUD’s NSPIRE notices and guidance
A new interagency agreement could eventually reduce duplicative reviews for certain federally financed housing projects.
HUD and the U.S. Department of Agriculture (USDA) signed a memorandum of understanding on September 29 to begin implementing provisions of the 21st Century ROAD to Housing Act aimed at improving coordination between the two agencies.
The agreement establishes a framework for evaluating opportunities to streamline environmental reviews and physical inspections for housing projects involving both HUD and USDA.
Among the areas the agencies plan to explore are greater coordination of environmental assessments, recognition of certain environmental review findings, and opportunities to conduct joint property inspections.
For multifamily projects combining HUD and USDA resources, the initiative could eventually reduce duplicative review requirements and administrative friction. The agreement begins that process, rather than immediately changing transaction requirements.
Sponsors pursuing projects involving both agencies should watch for implementation guidance establishing when coordinated reviews or inspections may be available. Any resulting changes could affect the documentation, review processes, and timing associated with qualifying transactions.
Read HUD’s announcement on the HUD-USDA agreement
Recent changes to FHA multifamily financing are creating new opportunities for borrowers, from more favorable underwriting terms to clearer eligibility requirements for build-to-rent communities. Alongside ongoing efforts to streamline reviews and transaction execution, these developments are strengthening FHA’s position as a financing option for multifamily sponsors.
As HUD continues implementing additional changes, FHA has the potential to become a more competitive option for your next multifamily transaction, whether you’re evaluating new construction, substantial rehabilitation, an acquisition, or refinancing. We’ll continue sharing the latest developments and what they could mean for your financing options in future editions of HUD Insights.
With X-Caliber’s experience as a direct FHA lender and servicer and our in-house underwriting expertise across FHA 221(d)(4), 223(f), and 223(a)(7), we can help you navigate these changes and evaluate how FHA financing fits your goals.